
What a brutal six months it’s been for The Real Brokerage. The stock has dropped 23.5% and now trades at $19.06, rattling many shareholders. This might have investors contemplating their next move.
Is now the time to buy The Real Brokerage, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Is The Real Brokerage Not Exciting?
Despite the more favorable entry price, we’re sitting this one out for now. Here are two reasons we avoid REAX, plus one stock we’d rather own.
1. Breakeven Operating Margin Raises Questions
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
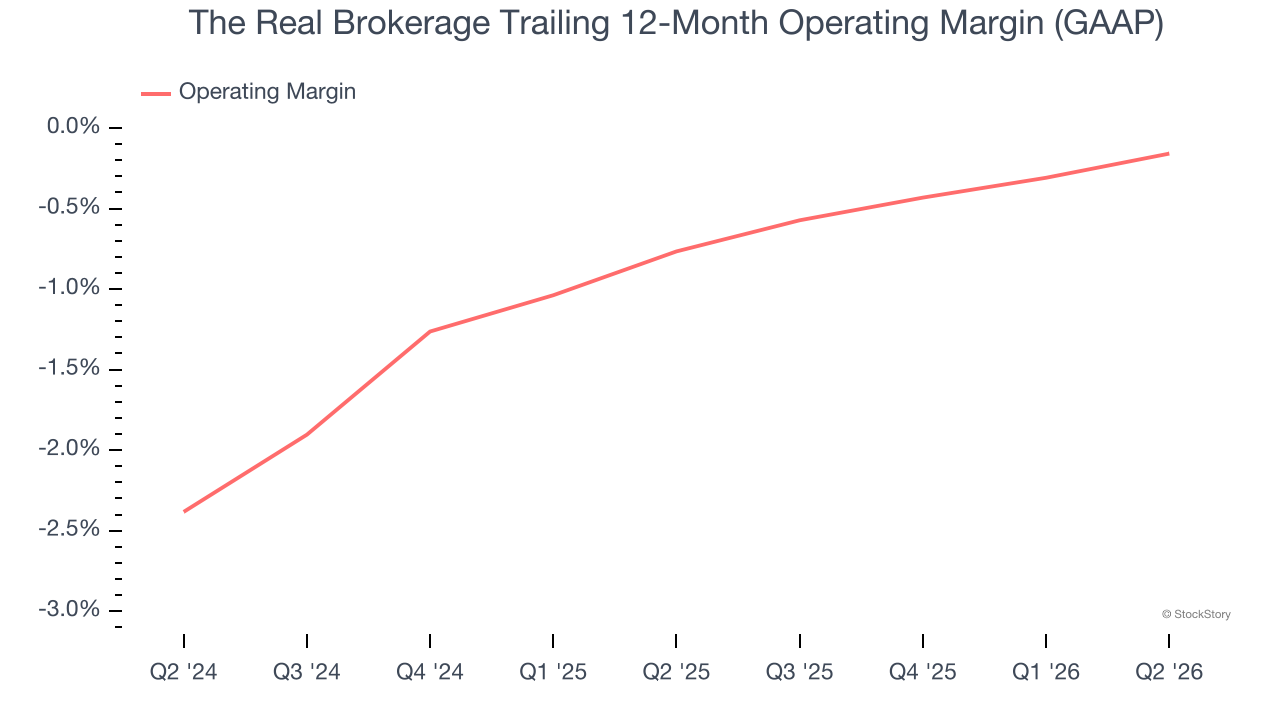
The Real Brokerage’s operating margin has generally stayed the same over the last 12 months. The company broke even over the last two years, inadequate for a consumer discretionary business. Its large expense base and inefficient cost structure were the main culprits behind this performance.
2. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
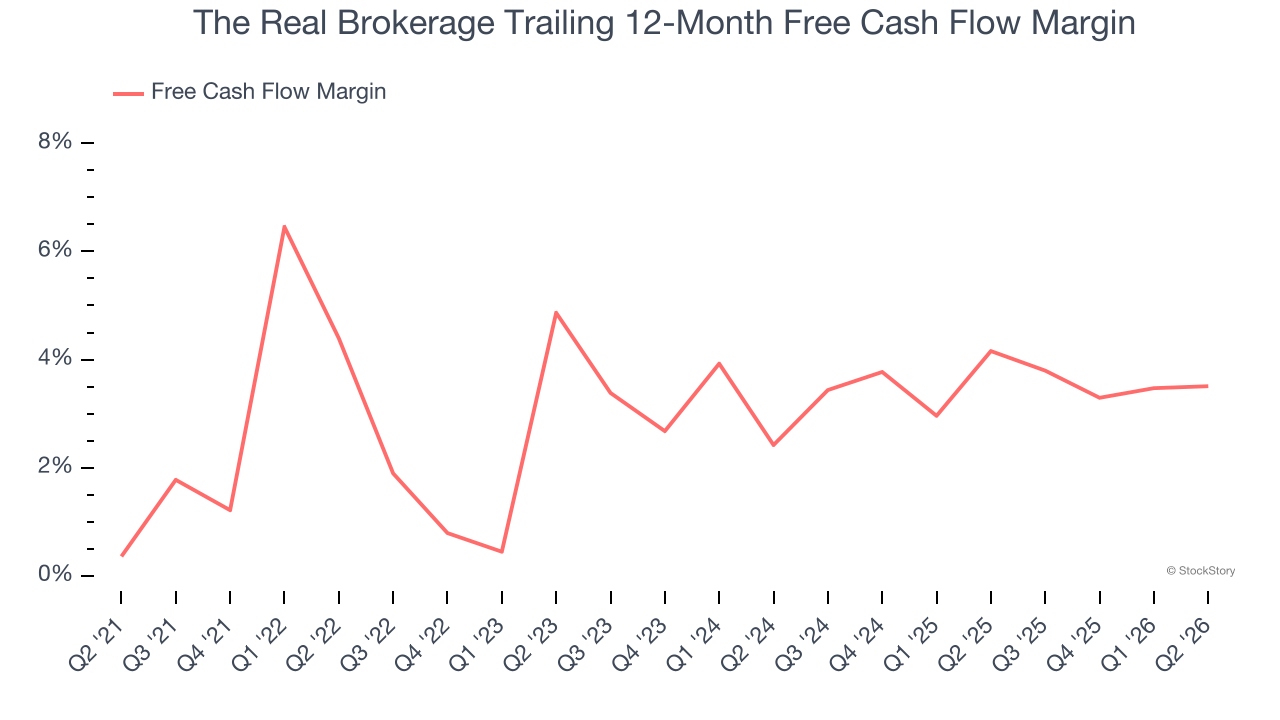
The Real Brokerage has shown poor cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 3.8%, below what we’d expect for a consumer discretionary business.
Final Judgment
The Real Brokerage’s business quality ultimately falls short of our standards. After the recent drawdown, the stock trades at 1.7× forward EV-to-EBITDA (or $19.06 per share). This valuation multiple is fair, but we don’t have much faith in the company. We’re pretty confident there are superior stocks to buy right now. We’d recommend looking at the Amazon and PayPal of Latin America.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.